Bank of America Hit with $1.2 Billion Penalty for Money Laundering Violations
The US Treasury Department has imposed a staggering penalty of over $1.21 billion against Bank of America, the second-largest bank in the United States, for violating anti-money laundering and sanctions laws. This fine, announced on Tuesday, represents the third-largest penalty in the history of the Treasury Department, highlighting the severity of the bank's compliance failures.
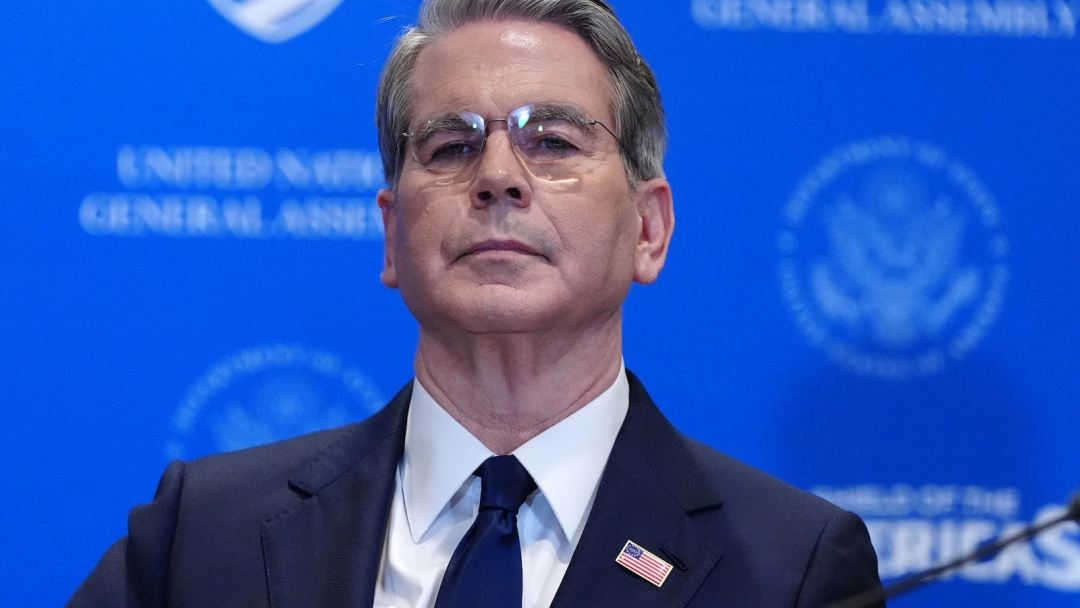
US Treasury Secretary Scott Bessent emphasized the far-reaching consequences of such failures, stating, "When a bank of this size fails to meet its anti-money laundering and sanctions obligations, the consequences extend far beyond its own walls, exposing the entire US financial system to significant illicit finance risks." His comments reflect a growing concern about the integrity of the financial system amid increasing scrutiny of large banks.
Explore on Amazon
Amazon shopping links. As an Amazon Associate I earn from qualifying purchases.
The Financial Crimes Enforcement Network (FinCEN) assessed a $1.2 billion penalty against Bank of America due to its inability to adequately mitigate and report on significant national security risks, particularly those related to Chinese Money Laundering Networks and illicit finance activities along the US-Mexico border. The deficiencies identified by FinCEN included serious lapses in the bank's processes for identifying and reporting suspicious transactions, as well as shortcomings in customer due diligence practices. Notably, the bank reportedly failed to report over $5 billion in suspicious transactions to FinCEN in a timely manner.
In addition to FinCEN's penalties, the Office of the Comptroller of the Currency (OCC) imposed a historic fine of $750 million on Bank of America for its ineffective anti-money laundering compliance program. This OCC fine is included in FinCEN's total penalty, which also encompasses an $11.6 million settlement agreement with the Office of Foreign Assets Control (OFAC) over apparent violations of various sanctions programs, including those related to Iran, Russia, and global terrorism.
Bank's Commitment to Compliance Enhancements
Bank of America has agreed to settle 475 apparent violations of multiple sanctions programs and has committed to significant compliance improvements, including enhanced training, testing, and audit measures. In response to the penalties, the bank stated, "Financial crime compliance is serious, and we are responsible for getting it right. We have invested billions of dollars in technology and dedicated thousands of employees to combat financial crime, and our team is far along with and committed to completing the work required to address the issues raised by our regulators."
The Unraveling
The Treasury's actions serve as a stark reminder of the importance of compliance with US anti-money laundering and sanctions regulations. The penalties imposed on Bank of America not only reflect the bank's failures but also underscore the potential risks posed to the broader financial system when major institutions neglect their responsibilities. As the landscape of financial crime continues to evolve, the repercussions of these violations may have lasting implications for the bank and the industry at large.
As investigations into the bank's practices continue, questions remain about the effectiveness of its compliance measures and the potential for future violations. The case serves as a critical example of the need for robust oversight in the financial sector, particularly as regulators seek to mitigate the risks associated with illicit finance. The ongoing scrutiny of Bank of America may lead to further revelations about the bank's operations and its commitment to preventing financial crimes.